October 28, 2026
Understanding what determines the cost of car insurance can help drivers make informed decisions about their coverage and household budgets. Premiums are calculated using several factors, including driving history, vehicle characteristics, location, coverage selections, and personal circumstances. Although some of these details are within a driver's control, others depend on external conditions or insurance company guidelines. Comparing options from different auto insurance agencies can help drivers understand available policies and identify coverage that fits their needs. It is also important to recognize that the cheapest policy is not always the most suitable choice, especially when it provides limited protection after an accident. Reviewing policy details, deductibles, exclusions, and liability limits can help prevent unexpected expenses. Drivers who understand how insurers assess risk are better prepared to ask useful questions and evaluate their options. By examining the main factors that influence premiums, motorists can make more confident decisions about protecting themselves and their vehicles.
1. Understanding the Role of Driving History
A driver's record is one of the important considerations insurers may use when determining premiums. Accidents, speeding tickets, reckless driving violations, and other incidents can indicate a greater likelihood of future claims. Drivers with a history of responsible behavior may qualify for more favorable rates, depending on the insurer's underwriting guidelines. When comparing policies, auto insurance agencies may review driving records to determine eligibility, pricing, and available discounts. A single violation does not affect every driver in exactly the same way because insurers use different rating methods. The severity and frequency of incidents, along with the time since they occurred, can influence how much a premium changes. Maintaining safe driving habits and avoiding distractions can help reduce accident risks over time. Reviewing a driving record for errors may also be worthwhile if an incorrect incident appears in the information used for an insurance quote.
2. Evaluating Vehicle Type and Repair Costs
The vehicle a person drives can influence insurance costs because different cars present different risks and potential claim expenses. Insurers may consider a vehicle's market value, repair costs, safety features, theft rates, and performance characteristics when calculating premiums. A luxury vehicle with specialized components may cost more to repair than a common model with readily available parts. Similarly, vehicles that are frequently targeted for theft may carry different comprehensive coverage costs. Drivers researching coverage through auto insurance agencies should provide accurate information about their vehicle's make, model, year, and equipment. Advanced safety features may help reduce certain risks, although their effect on premiums varies by insurer and coverage type. Before purchasing a new vehicle, comparing insurance estimates can reveal significant differences between models. This step allows buyers to consider ongoing insurance expenses alongside the purchase price, fuel costs, and routine maintenance.
3. Considering Location and Local Driving Conditions
Where a vehicle is primarily driven and parked can affect the price of an insurance policy. Urban areas with heavier traffic, higher accident frequencies, or greater vehicle theft rates may present different risks than rural communities. Weather conditions can also contribute to claims, particularly in areas that experience hail, flooding, severe storms, or icy roads. Insurers may use location-based information to estimate the likelihood and potential cost of future losses. When reviewing quotes, auto insurance agencies may ask for a residential address and details about where the vehicle is usually kept overnight. Even neighborhoods within the same city can have different risk profiles. Drivers should provide accurate location information because using an incorrect address may affect coverage or claim handling. Although motorists cannot control local traffic or weather patterns, they can consider secure parking, safe driving routes, and appropriate coverage for regional hazards.
4. Reviewing Coverage Limits and Deductibles
The types and amounts of coverage selected can significantly affect an insurance premium. Liability insurance generally helps cover eligible costs when a policyholder is legally responsible for injuries or property damage to others. Collision coverage can help pay for covered damage to the insured vehicle after a collision, while comprehensive coverage generally addresses certain non-collision losses, such as theft, hail, or falling objects. Policy requirements and available coverage options vary by state and insurer. Drivers comparing policies from auto insurance agencies should examine liability limits and consider whether they provide adequate financial protection. Choosing a higher deductible may lower the premium for certain coverages, but it also increases the amount the policyholder must pay out of pocket for a covered claim. A lower deductible may reduce that immediate financial burden while increasing the ongoing premium. Selecting appropriate limits and deductibles requires balancing monthly costs with the ability to handle unexpected expenses.
5. Understanding Mileage and Vehicle Usage
How frequently a vehicle is driven can influence the risk of an accident and, consequently, insurance pricing. Drivers who commute long distances may spend more time on the road than people who work remotely or use their vehicles occasionally. More time behind the wheel can increase exposure to traffic incidents, although individual driving habits and road conditions also matter. Insurers may ask about annual mileage, commuting distance, and whether a vehicle is used for personal, business, or commercial purposes. Some auto insurance agencies offer pricing programs or policy options that consider mileage or driving behavior. These programs may use an app, a connected device, or information supplied by the policyholder, depending on the insurer. Drivers should understand what data a program collects and how participation may affect their rates. Providing accurate usage information can help ensure that the policy reflects how the vehicle is actually driven.
6. Examining Claims and Vehicle Damage Risks
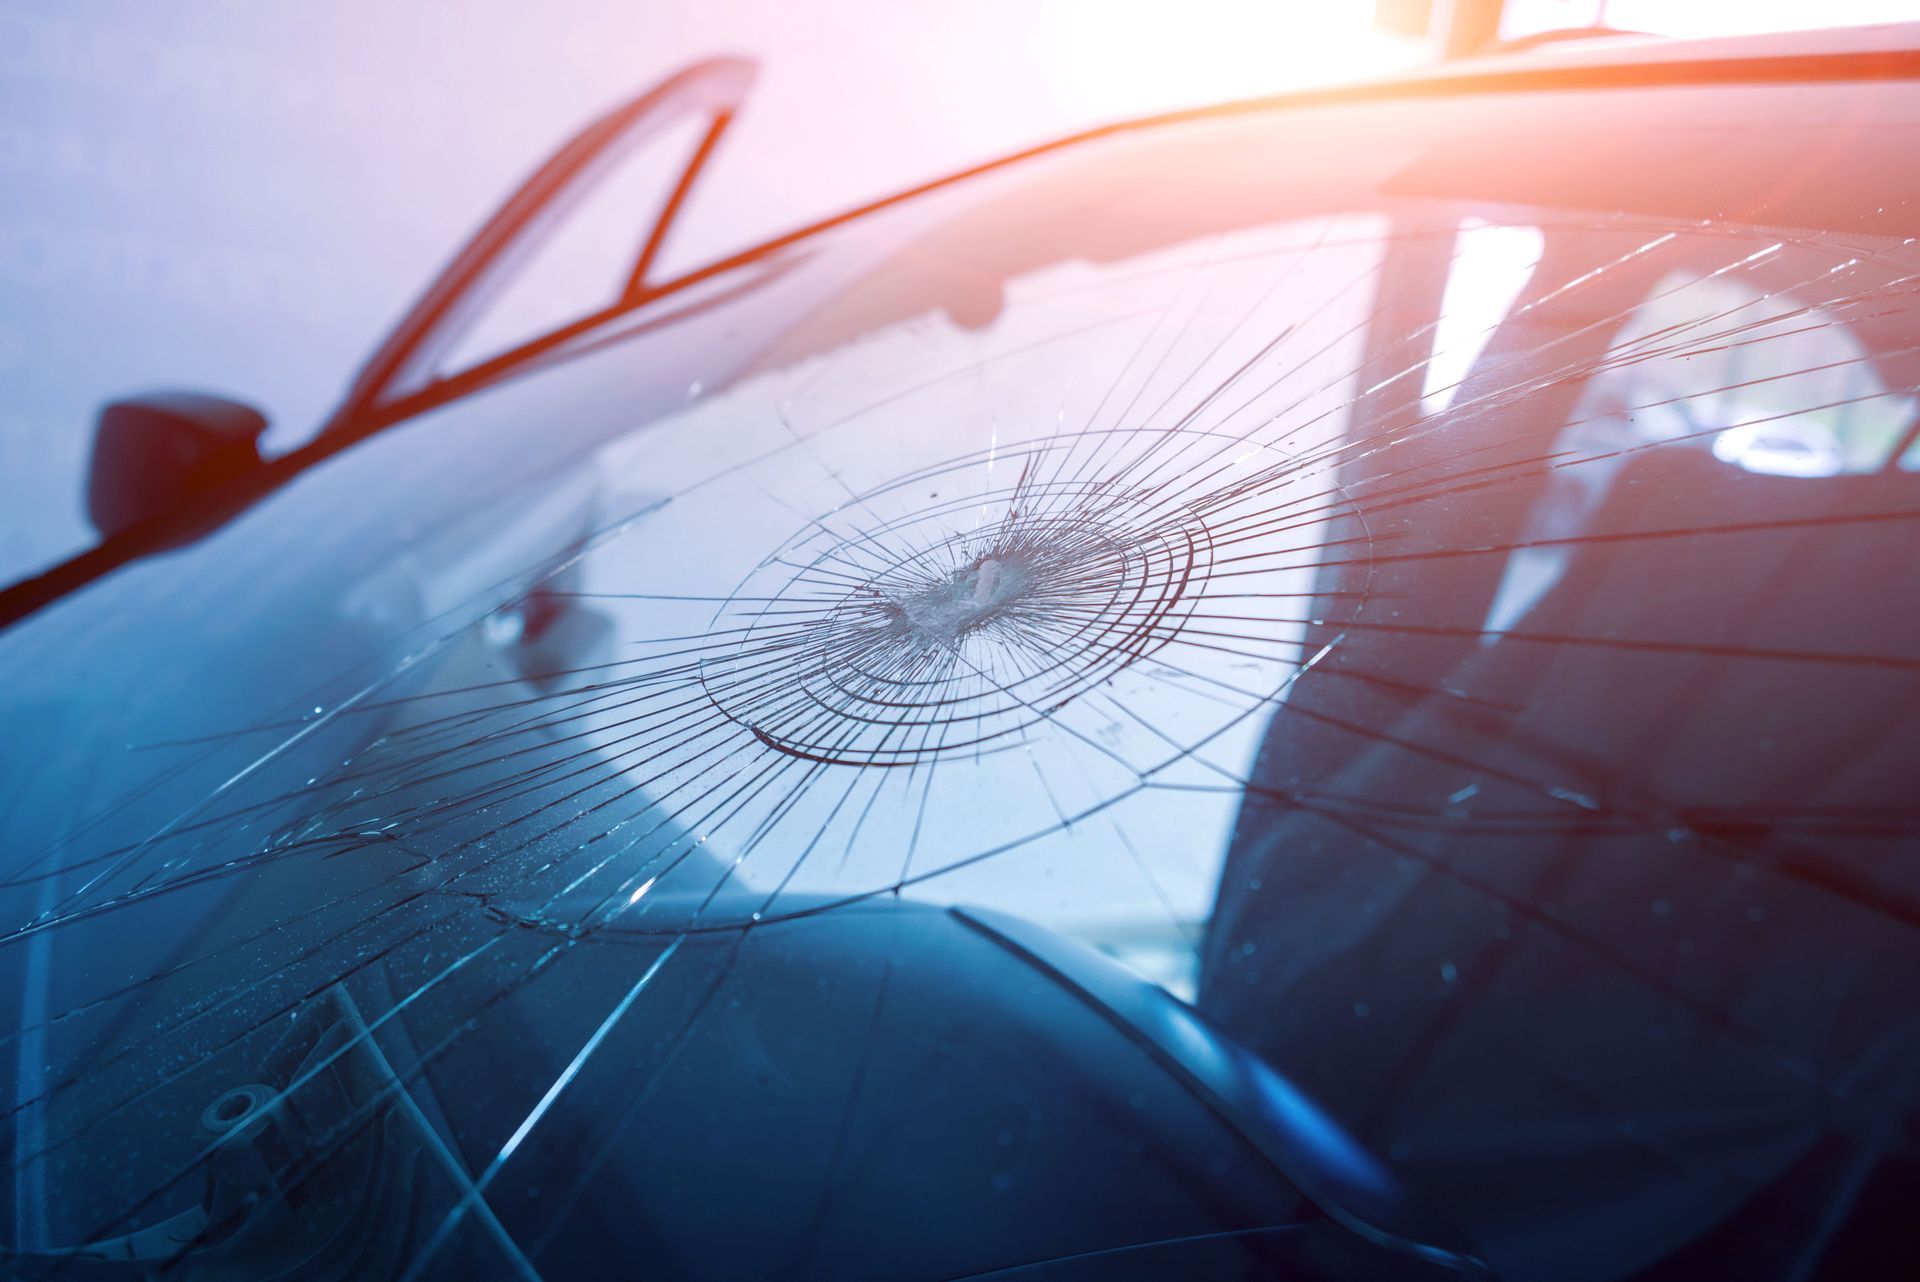
Insurance claims can affect premiums because they provide information about past losses and may influence an insurer's assessment of future risk. The impact of a claim depends on its circumstances, the coverage involved, applicable state regulations, and the company's rating rules. Some claims may affect rates differently from others, and not every incident automatically results in a premium increase. According to Insurance Journal, windshield damage represents 30% of automotive insurance claims, highlighting how frequently vehicle glass damage contributes to reported losses. Comprehensive coverage may help pay for eligible windshield damage, subject to the policy's terms, exclusions, and deductible arrangements. Drivers should review their policies to understand how glass repairs are handled and whether special deductible provisions apply. Promptly addressing small chips may also help prevent them from spreading into larger cracks that require more extensive repairs. Understanding the relationship between claims, deductibles, and coverage can help motorists make informed decisions when vehicle damage occurs.
7. Exploring Discounts and Savings Opportunities
Many insurers offer discounts that may help eligible drivers lower their premiums. Common opportunities include savings for bundling auto and homeowners or renters policies, insuring multiple vehicles, maintaining a qualifying driving record, or meeting certain mileage requirements. Some companies also provide discounts for approved safety features, defensive driving courses, or participation in specific telematics programs. Available savings differ, so drivers should ask auto insurance agencies which discounts apply to their circumstances. It is important to confirm the eligibility rules because not every discount is available in every state or applies to every coverage type. Combining policies can be convenient, but the overall cost should still be compared against separate policies from other providers. Drivers should also review discounts at renewal because eligibility and insurer programs may change. Regularly checking available savings can help households manage costs without automatically reducing important protection.
8. Considering Credit-Based Insurance Factors Where Permitted
In some states, insurers may use credit-based insurance information as one factor in pricing certain personal auto policies. This information is generally designed to help estimate insurance risk and differs from the credit score a lender may use when evaluating a loan. Its use is restricted or prohibited for auto insurance pricing in some jurisdictions, so the rules depend on where a policy is issued. Drivers comparing options through auto insurance agencies can ask whether this factor is considered and what information the insurer uses. Credit-based insurance information is not the only element in a premium calculation, and its impact varies among companies. Where permitted, reviewing credit reports for inaccuracies may be a useful financial habit, although correcting an error does not guarantee a specific insurance discount.
Contact Choice One Insurance Services to discuss your auto insurance needs, explore available coverage options, and find a policy that fits your circumstances and budget.